

Brief Takeaways:
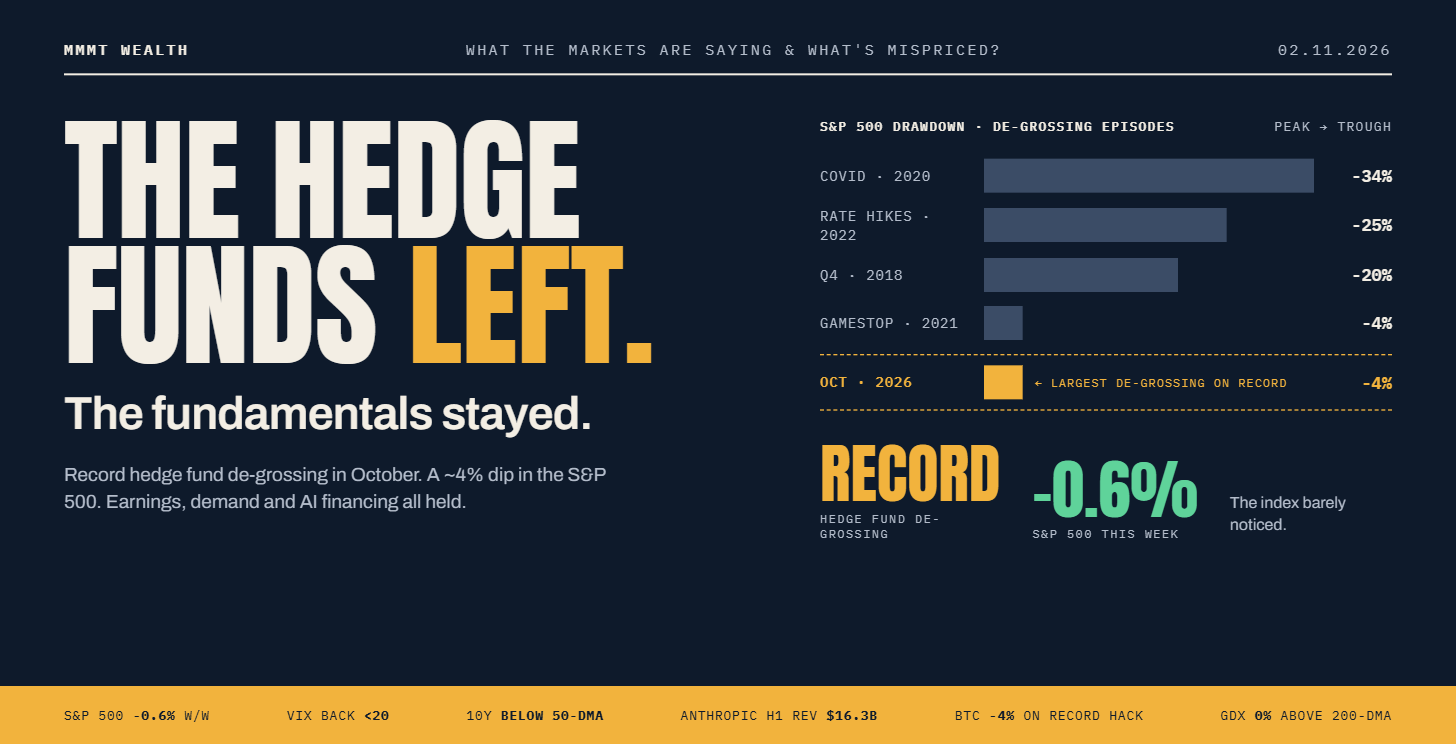
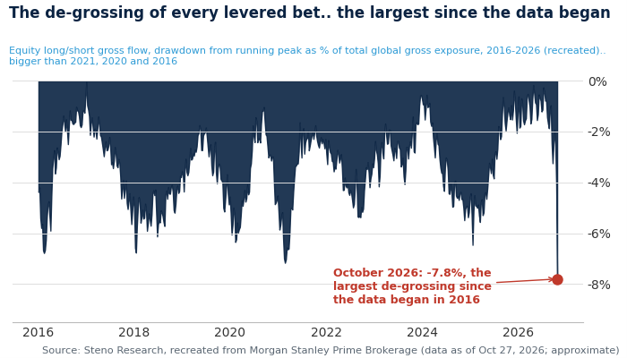
The forced selling looks close to being done. October saw the biggest cut to hedge fund exposure Morgan Stanley’s prime brokerage has on record…yet the SPY ended the week down less than 1% and sits still less than 4% away from highs.
We’re seeing more and more paths laid out to positive free cash flow for the hyperscalers over the next 2-3 years. AI financing will likely increase into 2027 before tapering off into 2028 where we will see a slow return to positive FCF.
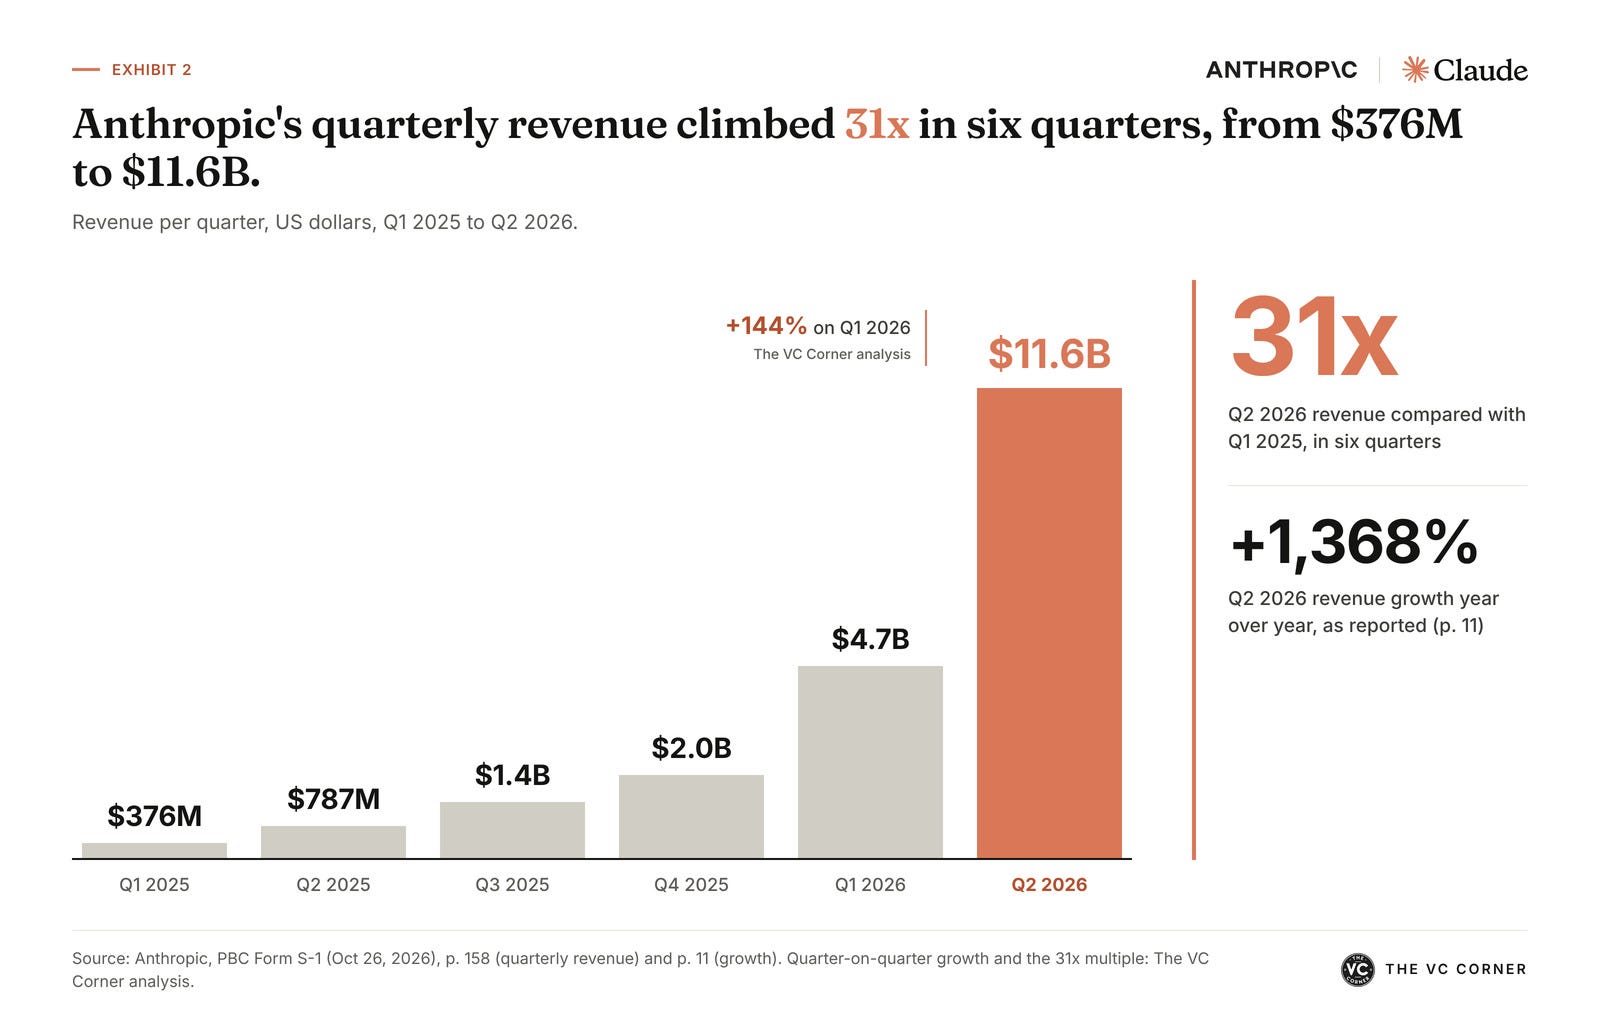
Anthropic’s S-1 should end the doomer question over whether AI will actually make money or not. Revenue is at $16.3B (which is up 14x YoY) with $132B in cash and investments.
Yields are slowly coming down and precious metals are about as oversold as they ever have been. When precious metals turn, relief elsewhere his historically followed.
Bitcoin barely flinched at the largest crypto exchange hack ever.
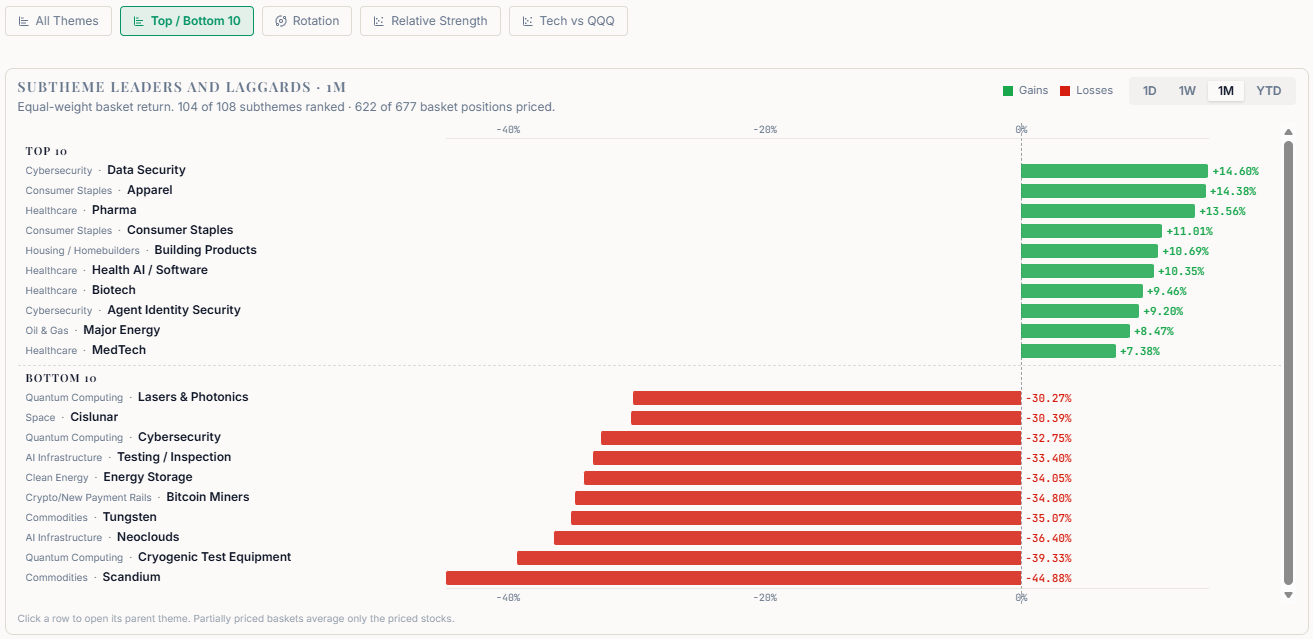
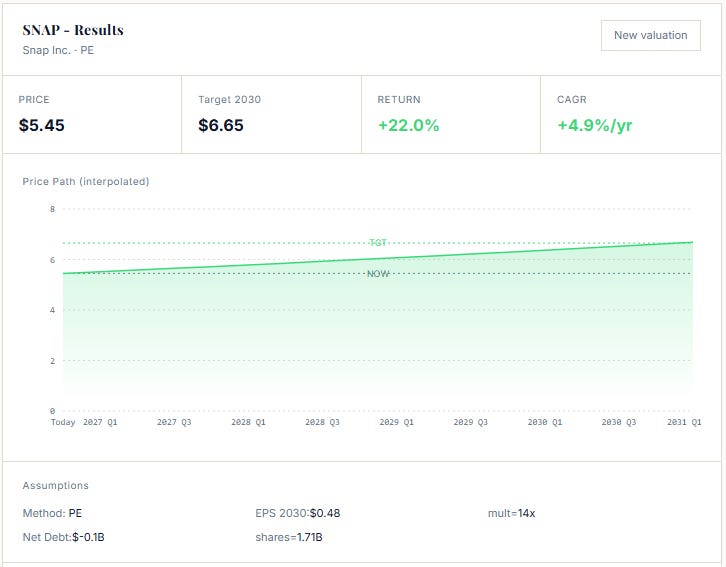
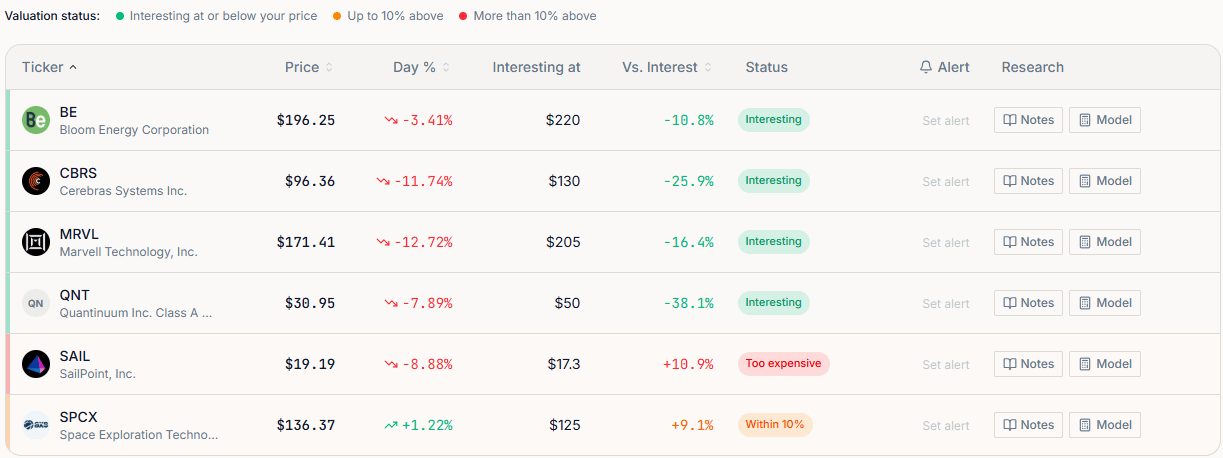
My web-app is being officially released tomorrow. Here’s some snips:
For your thematic check ins:
For your modelling help:
For your watchlist:
And much more.
For three weeks now, I’ve made the same argument.
This was never the AI bubble popping. It was hedge funds being forced out of the same crowded trade at the same time.
Last week was just more evidence of that happening.
Here’s what the headlines and noise told you:
Google (GOOGL) had its worst day ever.
Credit markets were “cracking.”
Neoclouds were “finished.”
The AI debt pile was about to “collapse.”
Here’s what actually happened:
The SPY finished the week down 0.6%…a smaller loss than the week before. It now sits less than 4% below its all time high.
Investment grade credit has barely moved. These are bonds issued by the strongest, most financially secure companies. The yield investors demand to them to them (as opposed to the US government) is close to where it was before October which is important because this is one of the first places we tend to see issues show up. So far, that’s not happening.
Real bubbles bursting look nothing like this. Every major bubble selloff in history was driven by the economy (COVID, 2022, late 2018) and they all ended with the index being down ~20-35%.
All these major selloffs also hit everything at once (index, small caps, housing, credit markets, earning estimates). It meant the VIX regularly spiked well above 30 and that investors were ultimately selling the entire economy rather than selling a portion of the market.
Today is completely the opposite:
The selling is concentrated. Two weeks ago when the QQQ sold off 3% in a single day, we saw 60% of SPY names finish green on the day.
The VIX has only briefly touched 20 before falling straight back down.
Earnings and earnings forecasts are rising…not being cut.
Is Deleveraging Finished?
Last week I said we were in the late innings but that we still had another week left in October.
This week I’m even more confident that we’re in the later innings…(though I will never call the bottom particularly with everything coming up in the week ahead).
Evidence behind this:
October was the biggest de-grossing month it has ever recorded meaning a huge amount of risk is already off the table amidst numbers that continue to impress even the most positive expectations.
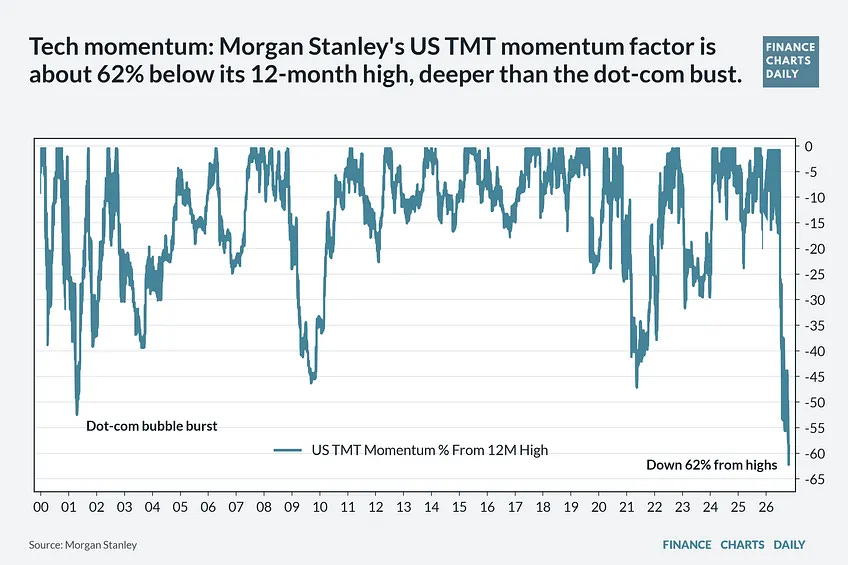
Momentum across the entire AI supply chain is as oversold as it has been all year.
Funds are measured month to month so now we’re in November…everyone has a clean slate to work from.
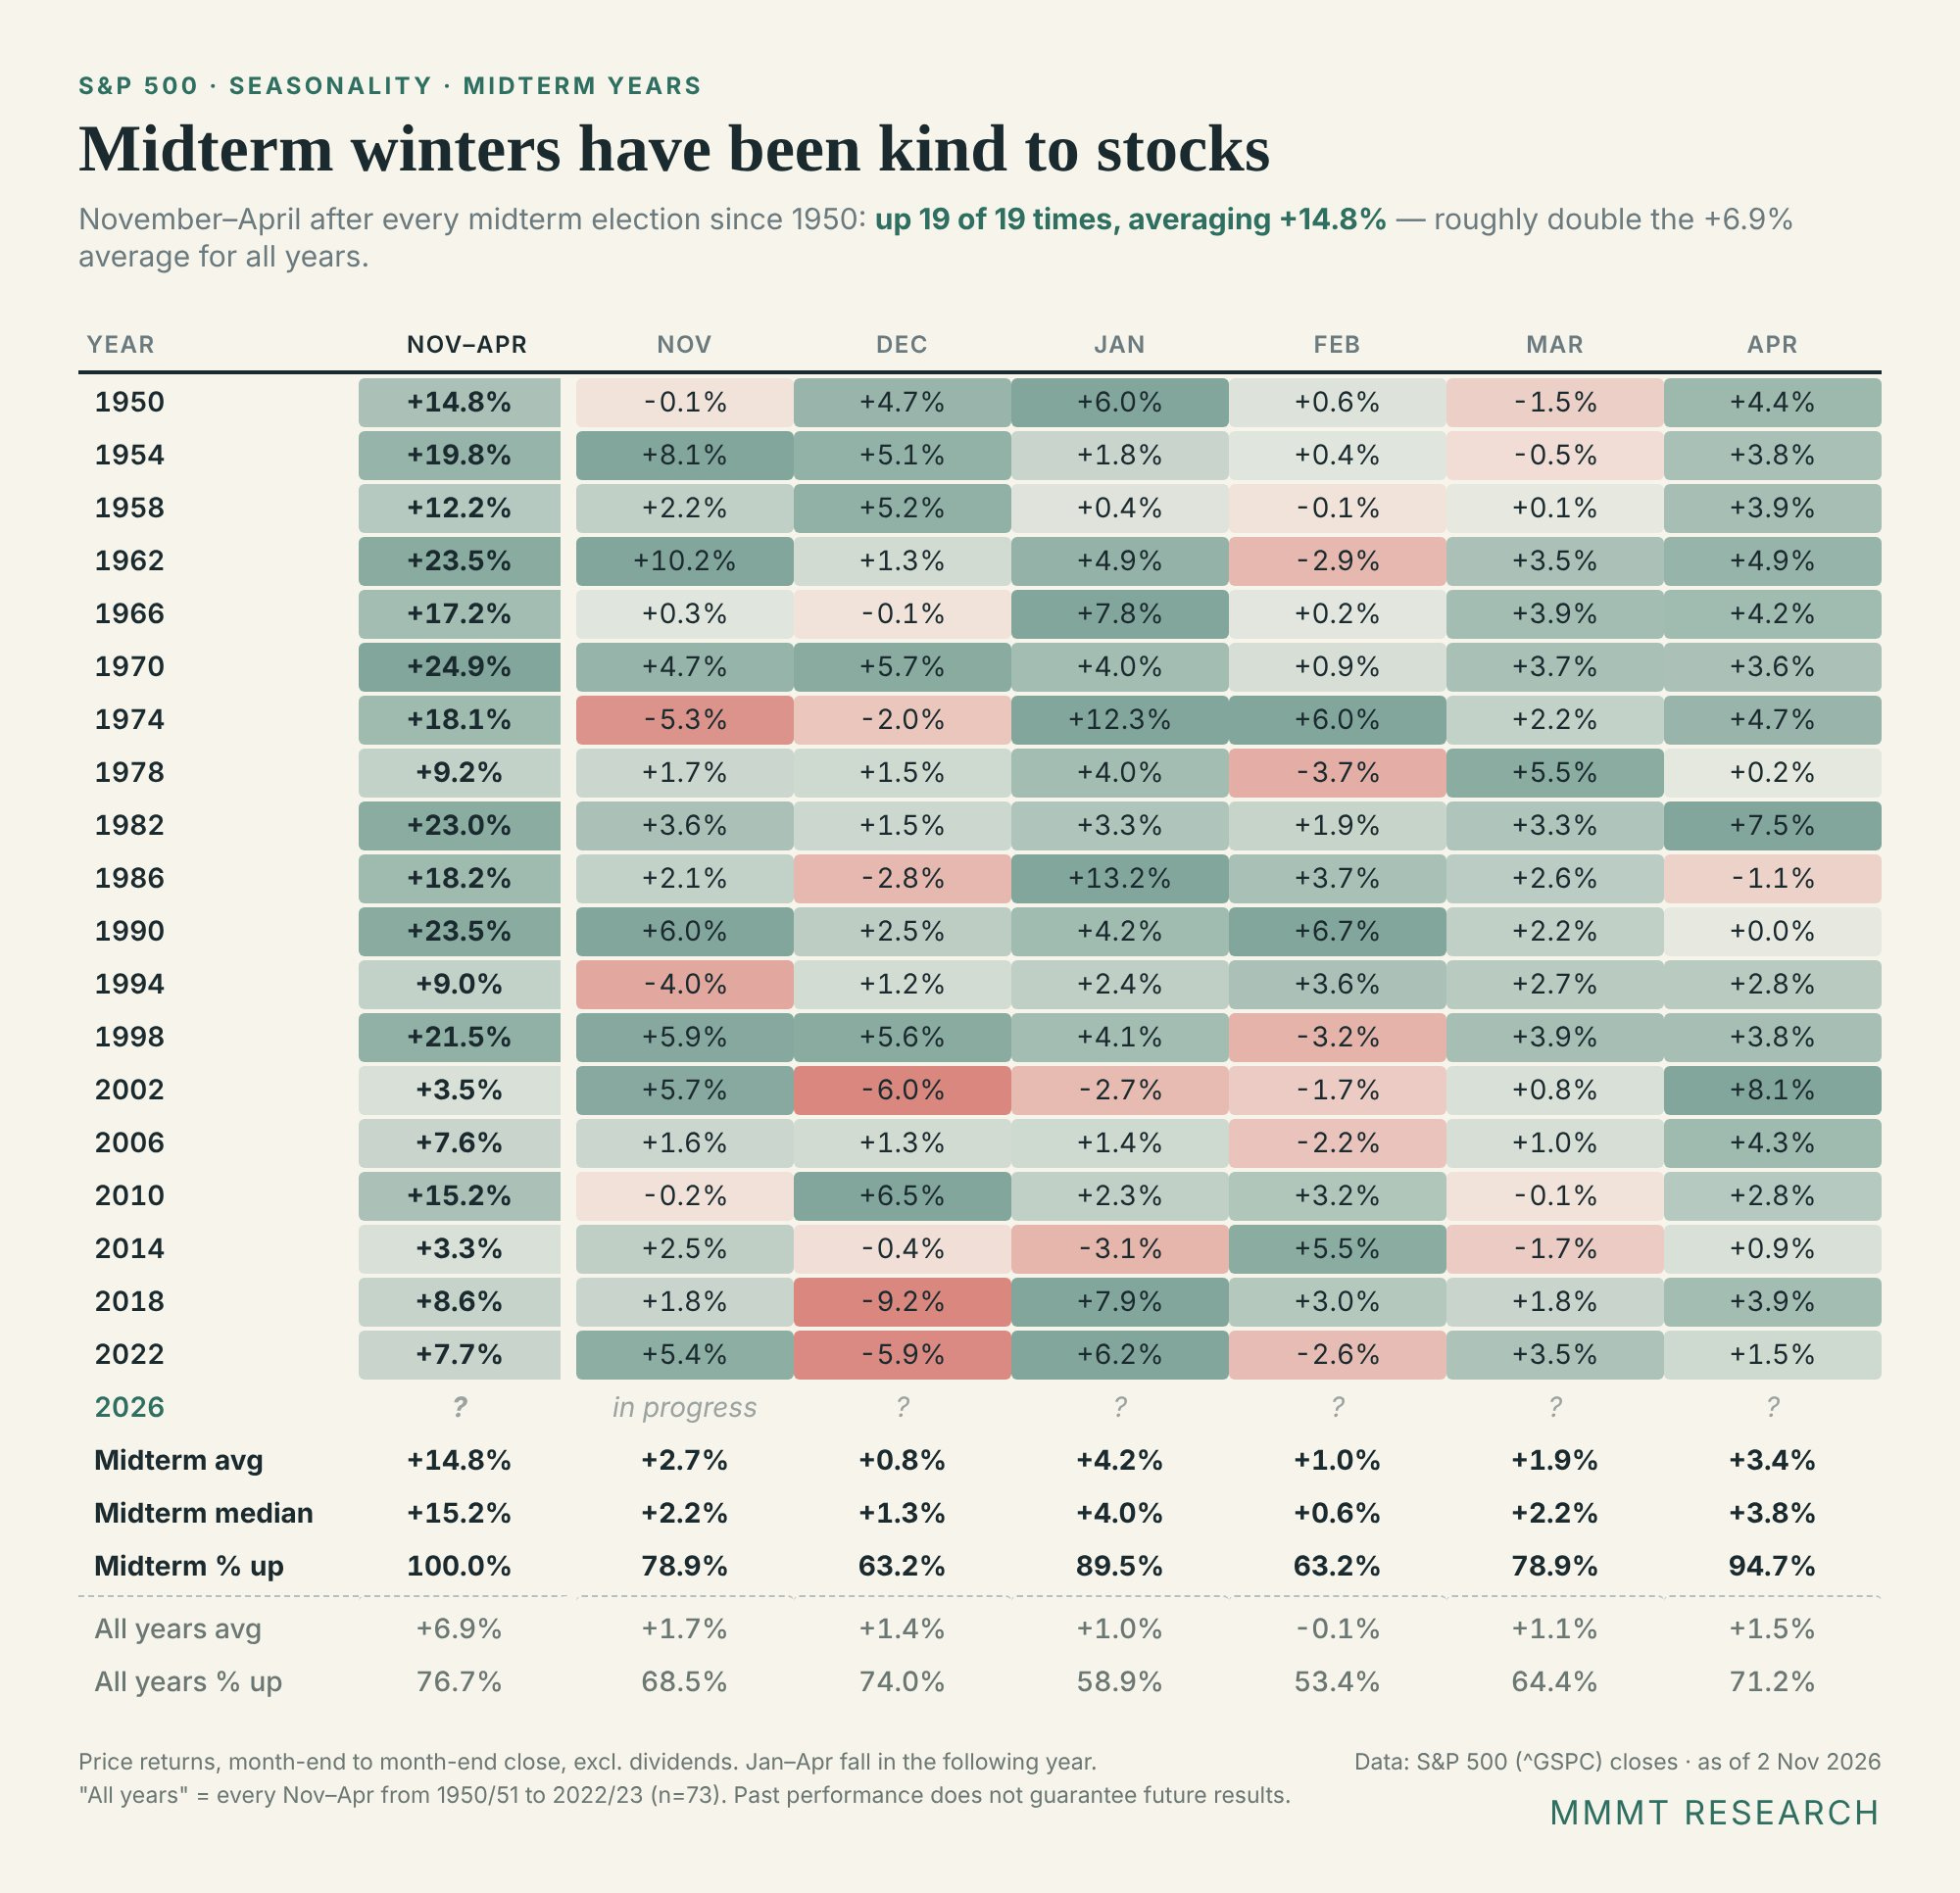
This doesn’t mean we’re at a bottom with midterms on Tuesday and the Iran headlines still being key market drivers. But the forced sellers are running out of things to sell.
Financing & Productivity
One of the many AI bear cases has always been that AI needs too much capital and that capital isn’t there.
Again, all data points against this:
AI-related debt issuance is now above $1T this year. There’s no argument against there being a shortage of capital. The problem is that it all came very quickly and came all at once to a concentrated pool of parties needing finance.
There’s plenty of capital. Goldman Sachs estimates ~$4.5T of raised capital across private credit, infrastructure, real estate. They expect private markets to do the majority of the heavy lifting in 2027.
Goldman expects 2027 to be the peak year of debt financing and after that they expect to see clear returns on that. Oracle (ORCL) is already laying out their roadmap to turn free cash flow positive again in H2 of 2028 after CapEx peaks in 2027. It targets more than $30B in free cash flow in FY29 which would be ~3x anything we saw before the CapEx boom.
And then there’s Anthropic.
Anthropic filed its S-1 last Monday which showed H1 revenue of $16.3B, or 14x YoY, and it had $132B in cash and investments at the end of June. A core bear argument is that the AI labs had signed up for spending that they couldn’t fund. This cash pile answered that bear argument.
Macro Update
Earnings remain as strong as ever. Q3 S&P 500 returns are growing in the 25-30% range and companies are continuing to guide higher.
EMCOR (EME), one of the biggest data centre electrical contractors, grew revenues 29% and raised full year EPS guidance by ~8%.
Eli Lilly (LLY) raised full year guidance.
SK Hynix profits rose 630% YoY at an operating margin of ~80%.
INNIO (INIO) data centre revenue jumped 12x in 1 year and it raised full year guidance to $4B.
Yields are slowly starting to turn. The 10-Year yield has slipped back below its 50 day moving average making lower highs and lower lows.
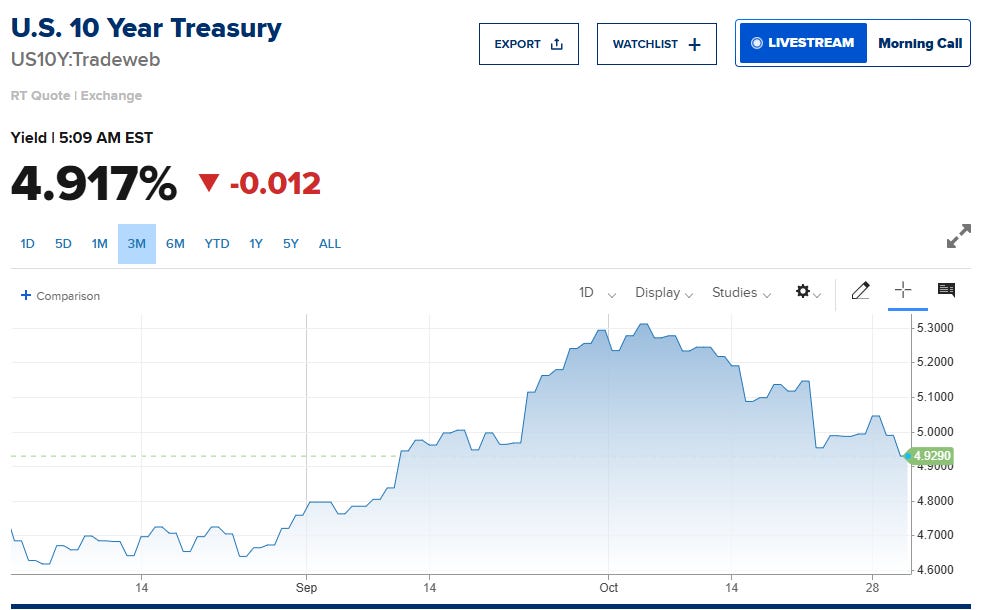
Corporate yields are important to watch here. CoreWeave’s (CRWV) bonds now yield over 15% and spreads on lowest-rated junk debt have spread to levels that do signal a funding strain. On the other hand investment grade credit has not moved materially. This is why it’s becoming increasingly important to own the highest quality balance sheets vs the most levered AI borrowers.
Important to watch this week:
The midterms on Tuesday. Expect volatility whatever the result.
Updates on the Iran situation.
Commodities
We remain bullish on silver, copper, solar, and scandium. I’m also watching gold closely for a clearer view on the macro.
Precious metals have had a very difficult period but we still remain very bullish on all names. We’ve focused on DCA’ing into silver, solar, and copper names so drawdowns aren’t as material as the actual drawdowns over the last 6 months.
A bottoming in gold and silver (and Bitcoin) will potentially show a good sign that the stress is easing across the entire market so this is something to keep a clear vision on.
Silver:
The structural case for silver remains unchanged for me. It’s in its fifth straight year of deficit with ~80% of it mined as a by-product so supply can’t respond. And with AI’s push for efficiency keeping silver demand higher, I remain with a very long-term bullish view on the precious metals markets.
Gold and silver are now ~2 standard deviations away below their 200D moving average. That is something that has barely happened in 40 years. On top of that we have 0% of gold miners (GDX) sitting above their 200D moving average. Again this is something that has barely happened before.
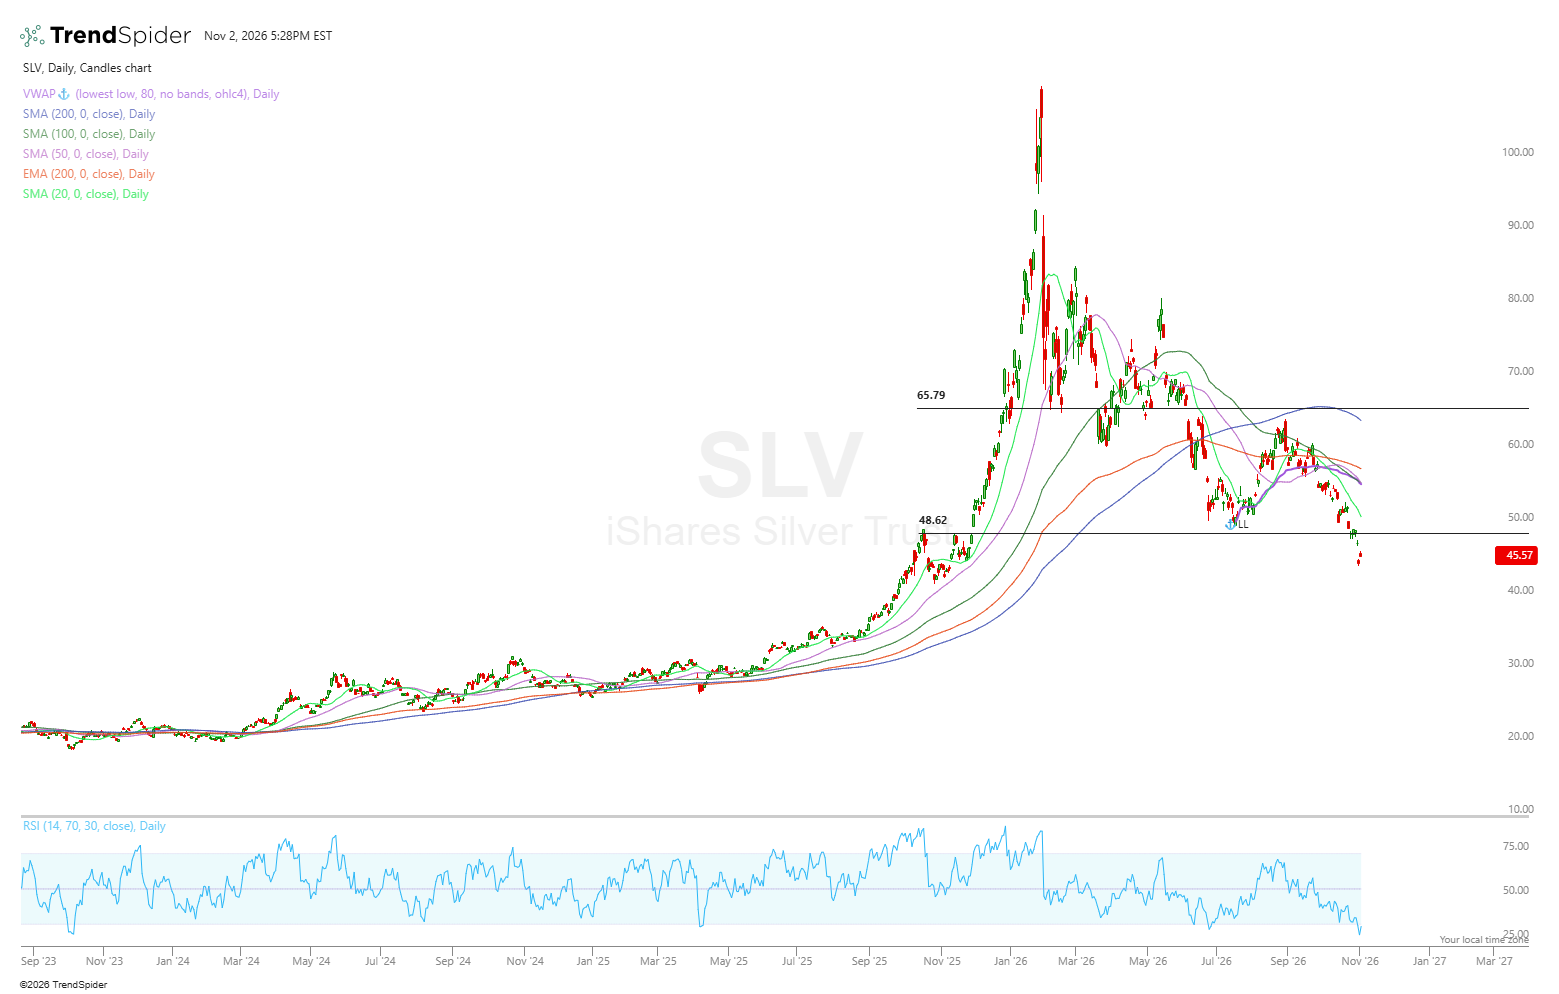
None of this confirms any bottoming but it does give confidence in saying we are much closer to the end of this sell off than the beginning.
Copper:
The physical copper market is extremely tight right now.
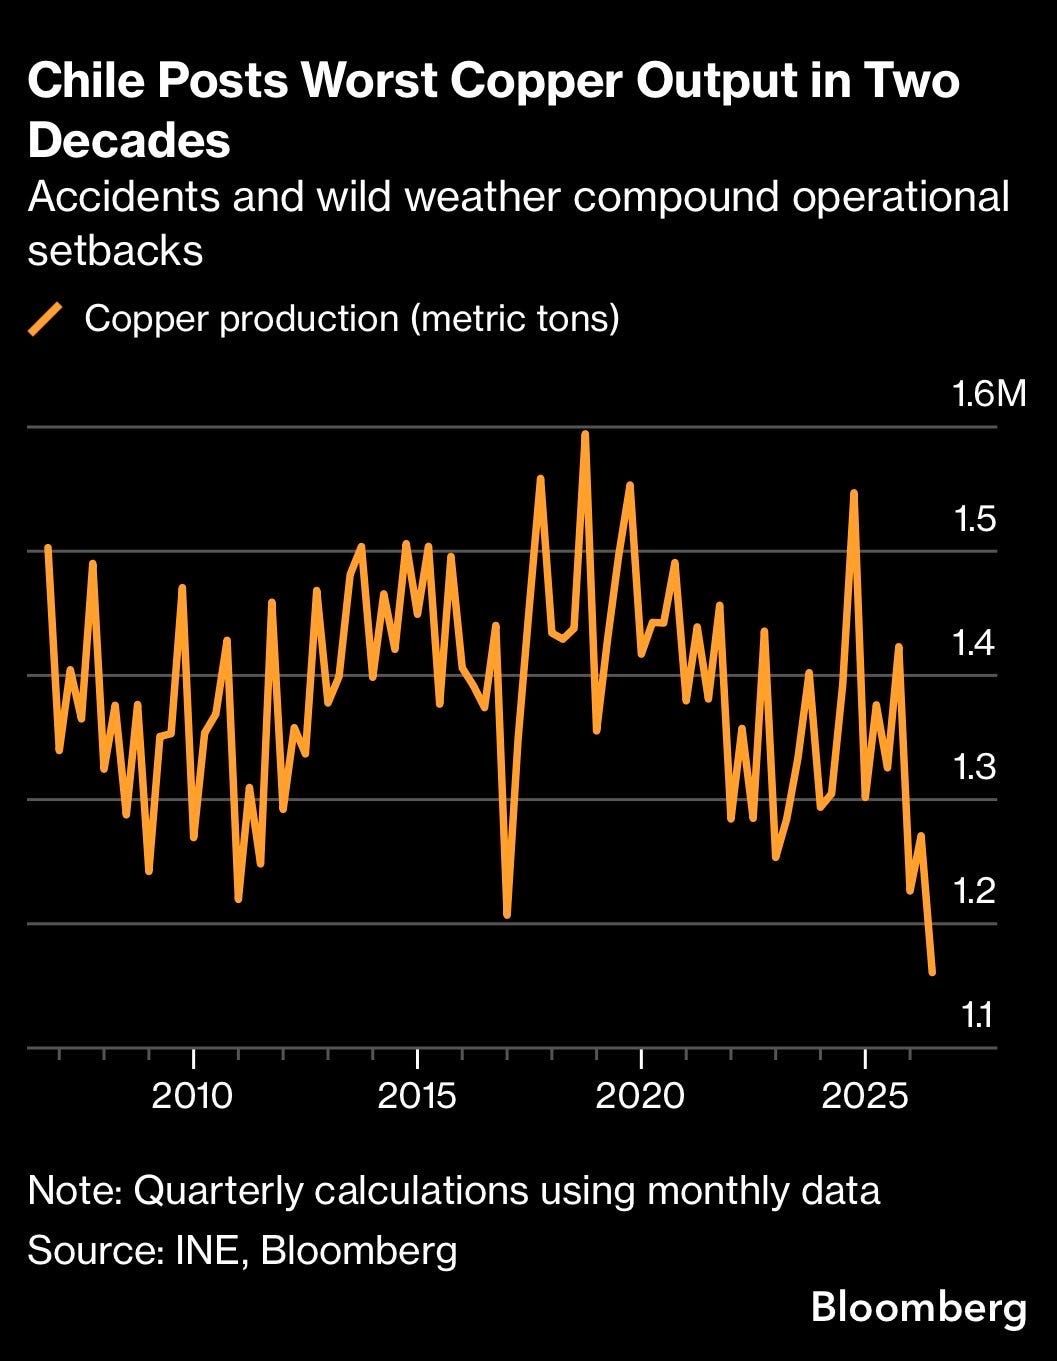
Supply is going backwards:
Chile (worlds largest copper producer with roughly one quarter of global mine supply) cut its 2026 production by another 330,000 tonnes to 4.94M which is a 6% cut and the weakest output in 20 years.
Buyers are evidencing that they want more copper than is currently available:
China is paying record prices to import copper. Chinese buyers are paying over the global benchmark price to get physical copper delivered into China. Buyers only pay this premium when demand is outrunning supply.
Crypto
Last week saw perhaps the largest test for crypto sentiment in recent history yet BTC finished the week only 4% down.
Binance saw the biggest crypto hack in history just a week after we heard narrative around quantum computing being able to break today’s cryptography by 2028.
Yet again…BTC held up far better than most of the market. This is more evidence against the “Bitcoin is too risky” crowd.
It’s also important to distinguish BTC from the Binance cyber attack. This sounds obvious but I’ve seen many claim they’re similar.
What’s Mispriced?
This is a section looking at the potential opportunities I’m seeing at the moment. I’ll split them by how I see the risk profile (high risk → low risk).
I aim for at least 3+ opportunities in every article I publish here, but that depends on what the market is offering at the time of writing.
You’ll also likely see overlap week to week. I am not a trader that changes his mind every few hours, days, or even weeks. If I see an opportunity, that opportunity sometimes stays around for weeks.
Last week we touched on:
NuBank (NU)
Applied Optoelectronics (AAOI)
Flotek Industries (FTK)
Applied Optoelectronics | AAOI (Medium Risk)
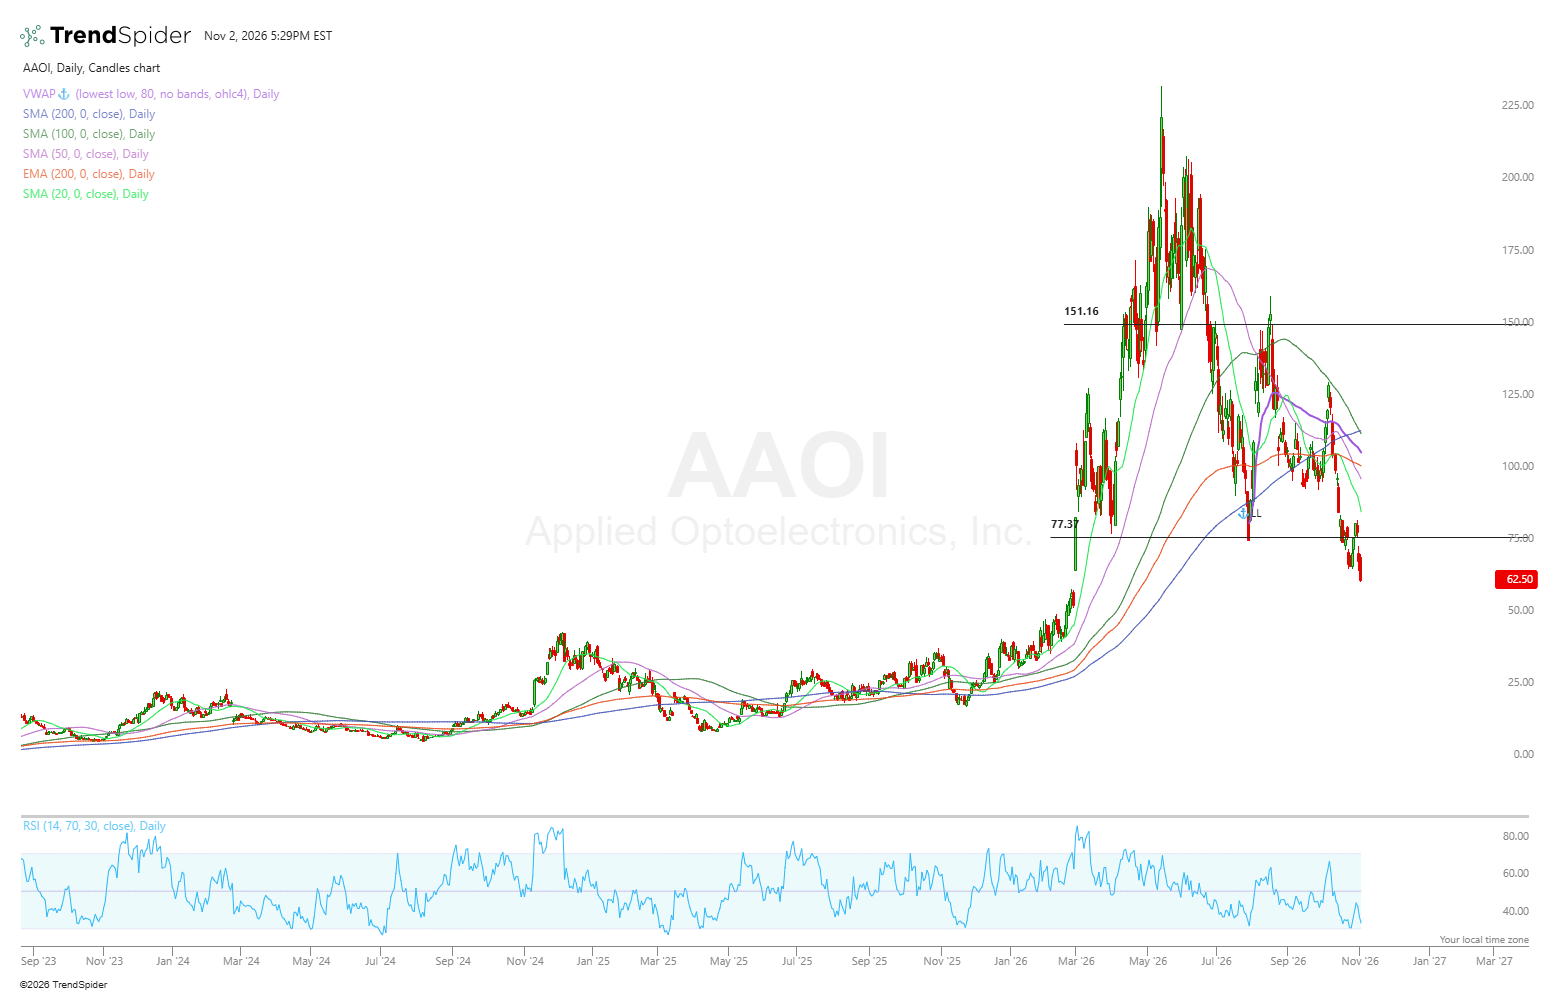
Please note that the below is not confirmed yet but over the last few days there’s been some bullish AAOI news circulating.
As per a retail analyst, a Wistron Group industry expert said Microsoft (MSFT) and Amazon (AMZN) have already reserved production capacity with AAOI because of AAOI’s US manufacturing footprint.
If this is accurate, it matters for two reasons:
Customers are already locking in future supply. Simply put, reserving capacity in advance isn’t what you do when you’re unsure about demand.
AAOI has diversification in customers across the AI buildout (Microsoft, Amazon, and also potentially AMD are a customer). Customer concentration has regularly been a key bear case amongst many in the AI supply chain.
This by no means completely de-risks the bear case that the market is focusing on right now but it adds another layer of confidence to my bull case.
AAOI reports earnings on Thursday and the market will be solely looking to see if we’ve seen material advancements towards management target of 930,000 units per month of 800G/1.6T transceivers by the end of 2027.
