

Brief Takeaways:
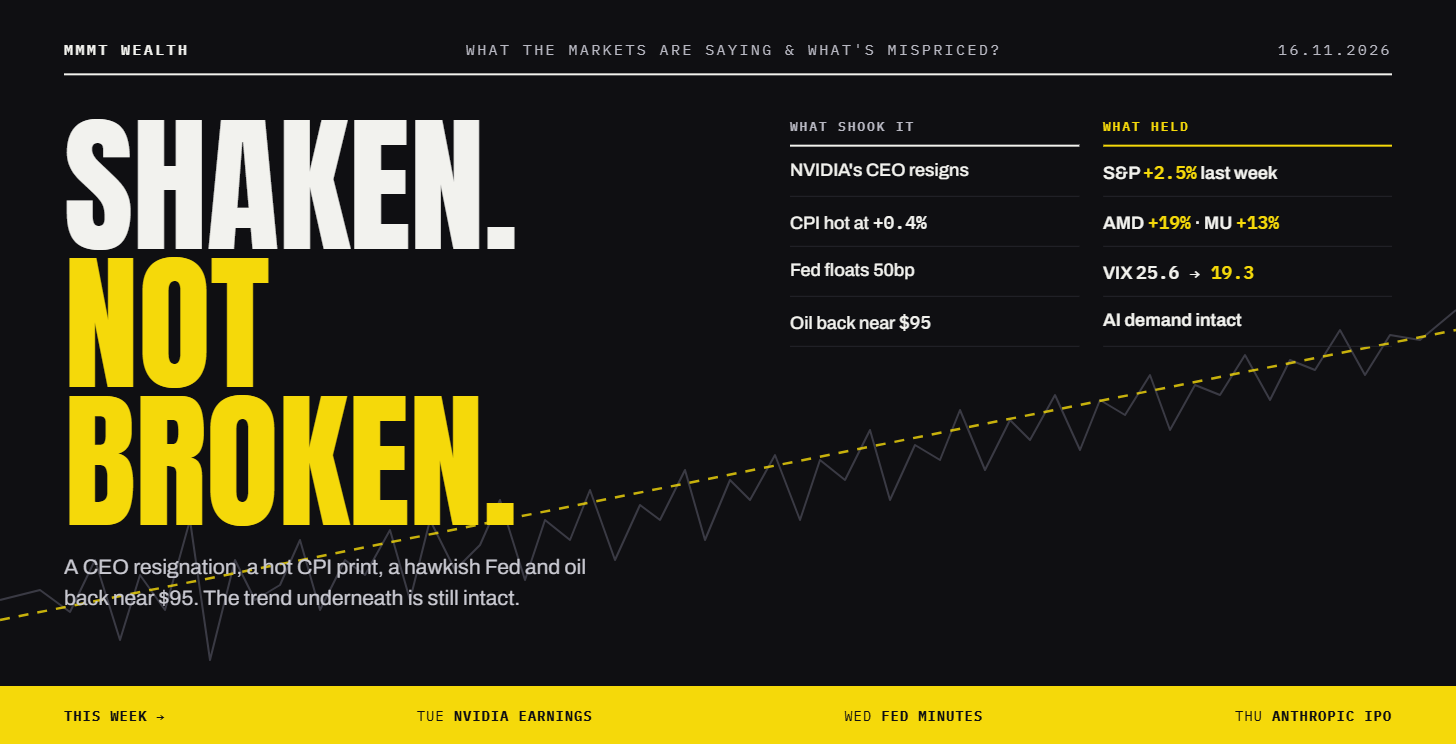
The forced selling thesis held up. Despite the fear in markets right now, the SPY had its best week since early August last week (+2.5%) through a CEO resignation, hot inflation data and talk of a 50bp Fed hike.
The AI trade bounced without NVIDIA. NVDA fell ~13% on the week, yet AMD rose ~19% and Micron ~13%. Capital isn’t leaving the AI trade as aggressively as people think. It’s rotating within it.
This week is the real test. NVIDIA reports today (its first earnings without Jensen Huang) and Anthropic lists on Thursday.
The Fed is now the biggest headwind. The 2-year jumped 34bp in a week, and a stronger dollar weighed on gold and Bitcoin.
Gold and silver are the most oversold since 2015. The timing is uncomfortable, but the setup keeps getting stronger and I’m not turning bearish on commodities.
Shaken But Not Broken
I delayed posting this piece till Tuesday morning because I wanted to see slightly more price action than when I normally post on Monday afternoons.
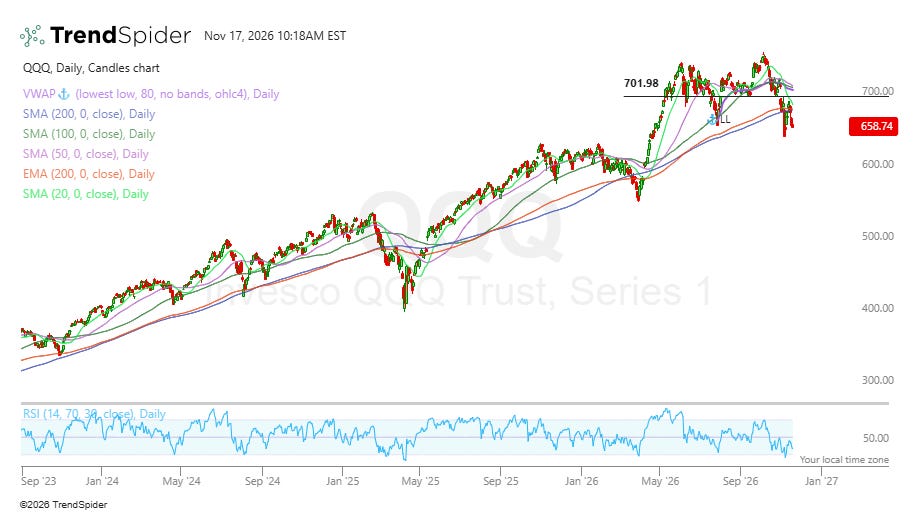
Yesterday was another blood bath but we’re still above the recent low from last Monday which we firmly finished the week above last week.
The main piece of worry I see is the growing rumours around an attack from Iran and/or a cyber attack. I can’t deny I’m a little spooked by the growing outages (Outlook, Workday, FAA, Chase, Zelle, United Airlines).
One of the main theories I’m seeing on these outages is that AI agents are starting to act on behalf of consumers... checking fares, rebooking flights, moving money, all by logging in as you. Banks and airlines aren’t keen on this because they’re losing control of the human.
Agents harm their systems far more than a normal customer would because they look a lot like fraud and they take away the upsell and loyalty these firms rely on. The theory is that they’re rushing out changes to block or control these agents, whilst skipping the usual testing. The fix works in testing but when millions of real customers hit it on a Monday morning…a hidden bug appears and the system falls over.
Nothing confirms this yet and it doesn’t fully explain the FAA outage but it would explain why the outages are clustering in banks and airlines and why each company has blamed a bug or a change on its own side rather than an attack. If it’s right, this isn’t a sign of something sinister... it’s potentially a sign of AI being adopted faster than old systems can handle.
On The Sell-Off
For five weeks I’ve said this was hedge funds being forced out of a crowded trade…not an AI bubble bursting. I still think that’s the case but just with a few more moving parts than before.
Last week was the real test of that view. We had endless “FUD” and retail panic, including:
NVIDIA’s CEO resigning. Jensen Huang stepped down on Thursday after 33 years. The story escalated far faster than anyone (myself included) expected.
Hot inflation. October CPI rose 0.4% (vs 0.3% expected) and core rose 0.3% (vs 0.2%).
A more aggressive Fed. Fed Governor Waller said a 50bp hike in December should be on the table.
Yields jumping (again). The 2-year rose 34bp to 4.85%, its biggest weekly rise in two years.
That’s a lot of bad news for one week…yet the SPY rose 2.5% and the QQQ 2.3% which is the best week since early August and the end of a four-week losing streak.
At the time of writing (early morning Tuesday) the QQQ has given back much of those gains but it’s still only down 1.7% over the last five trading days.
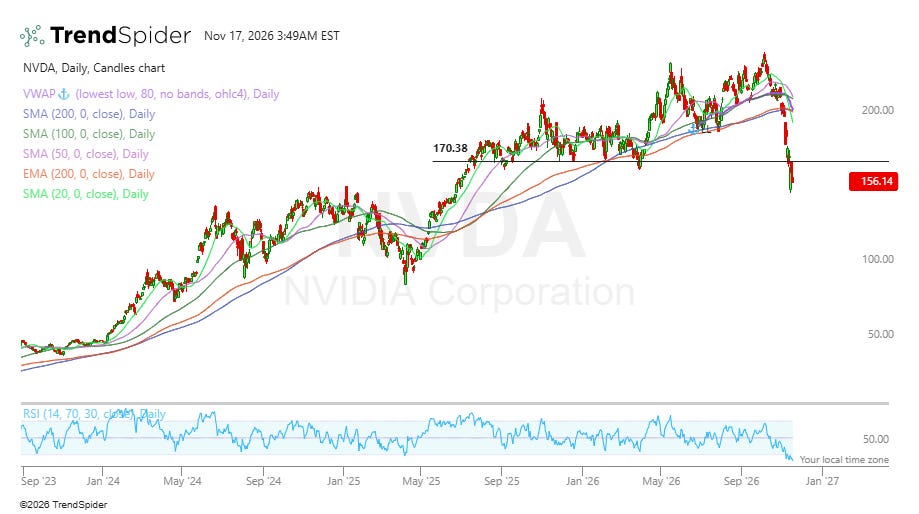
Underneath, NVIDIA fell ~13% on the week while AMD rose ~19% and Micron ~13%.
I’ll reiterate what I’ve said many times:
When forced sellers are in control, bad news gets punished across the board. When they’re done, the market starts looking through it. Last week looked a lot more like the latter.
The Week Ahead Is The Real Test
NVIDIA earnings (Tuesday): CFO Colette Kress is interim CEO and the board says it has no reason to believe national security was compromised.
I sold my NVDA position last week for a nice gain not because I think NVDA deserves to trade much lower. It’s because the risk of holding a position already well in the green started to outweigh the upside from here for me.
The leadership situation at NVDA is messy. On one side, Trump has said he “would certainly not mind” seeing Jensen return, and Elon Musk and a petition with 180,000+ signatures are backing him. On the other, the board says it is not considering his return. It’s running an investigation into his conduct and has started hiring a search firm for a new CEO. I wouldn’t rule a return out for Jensen but it’s certainly not something I’d be willing to base an investment thesis on.
If Jensen doesn’t come back, I think NVDA is fine for the next 18-24 months. Its chips are already designed and sold out and demand over that window shouldn’t change materially because of who the CEO is. Beyond two years is where leadership matters more: product bets, competitive positioning and keeping key engineers. That longer-term uncertainty is the other reason I felt the risk/reward no longer justified holding.
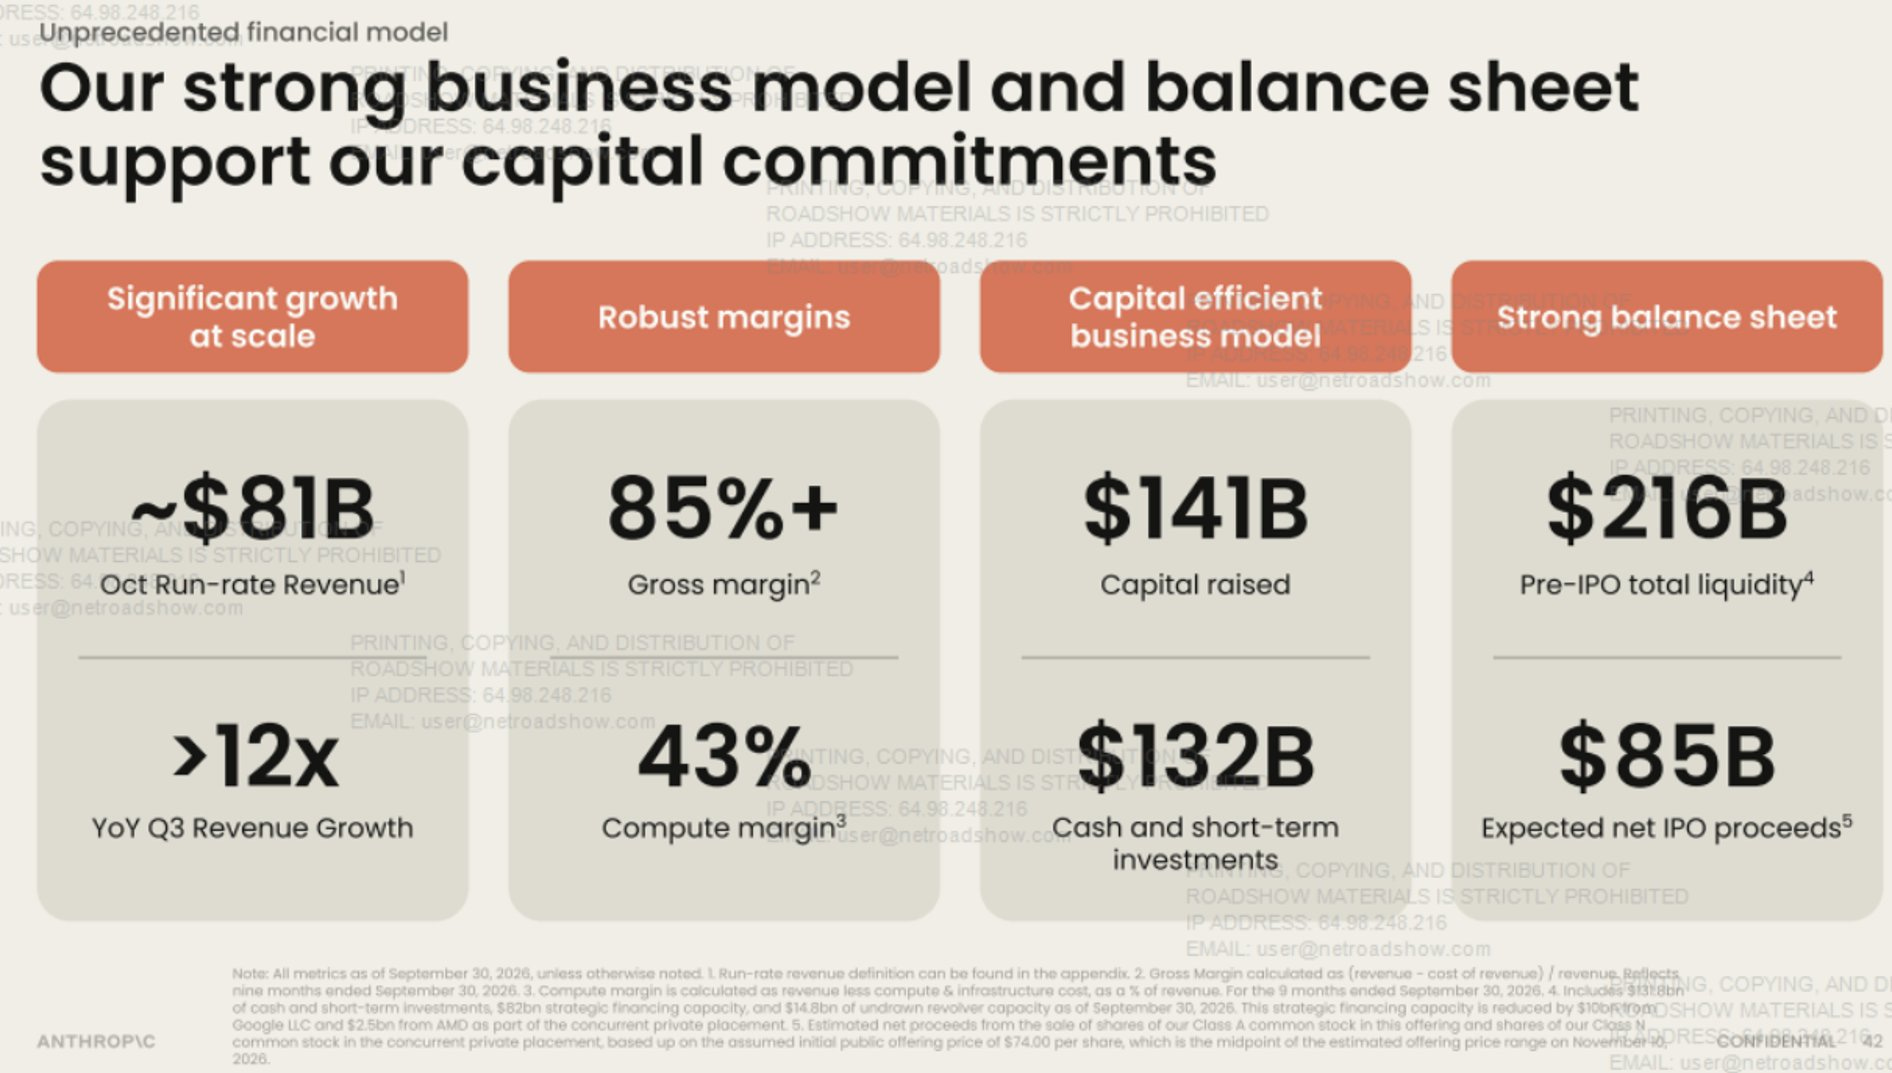
Anthropic IPO (Thursday): Anthropic lists under the ticker ANT at $70-78 a share valuing it at ~$1.3-1.45T. Early talk was as high as $2T.
Q2 revenue was $11.6B with a run-rate of ~$46B a year. That puts Anthropic at ~28-31x run-rate revenue…for a business growing ~14x year-on-year with $132B in cash and investments. Pricey on the surface, but high-growth software has regularly traded at 15-20x revenue while growing just 30-40% a year.
The bigger question is the size. At ~$60B, this is one of the largest share sales ever and its happening in a market that has been struggling with exactly this problem. Much of this year’s AI sell-off came from new supply: tens of billions in fresh shares and debt from AI companies hitting the market at once forcing investors to sell what they already owned to make room.
So Thursday is a test of demand as much as of Anthropic itself. Pricing at the top of the range and holding above the IPO price would tell us investors have the appetite (and the cash) to keep funding the buildout. A weaker debut would suggest the market still needs more time to digest all that supply.
Macro Update
The Fed is now the main headwind. Producer prices are up 6.5% year-on-year (the fastest since late 2022), and a 25bp December hike is now fully priced. The 10-year rose from 4.86% to 5.14% on the week.
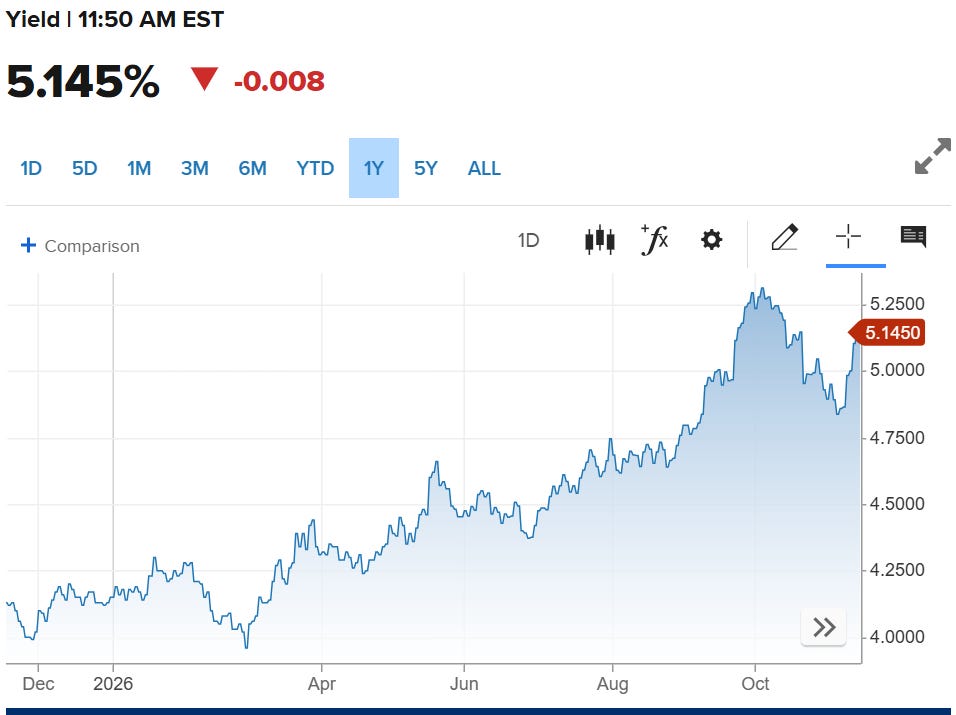
My view on yields hasn’t changed. An investment boom raises the neutral rate, so high yields alone aren’t a reason to be bearish on AI. But they do hit rate-sensitive assets hardest…and last week that included gold and Bitcoin.
The dollar did the damage. The dollar index rose 1.1% to 103.4, tightening liquidity for the assets most sensitive to it.
Asia is stepping in. Taiwan activated its ~$15B stabilisation fund and curbed short selling after heavy foreign selling. These governments clearly want to protect the capital markets funding the AI buildout.
Commodities
We remain bullish on copper, solar, scandium and precious metals.
Gold: gold is now more oversold relative to its 200-day moving average than at any point since the December 2015 bear-market bottom. Every ~10% fall below the 200-day since then has ended in a bottom.
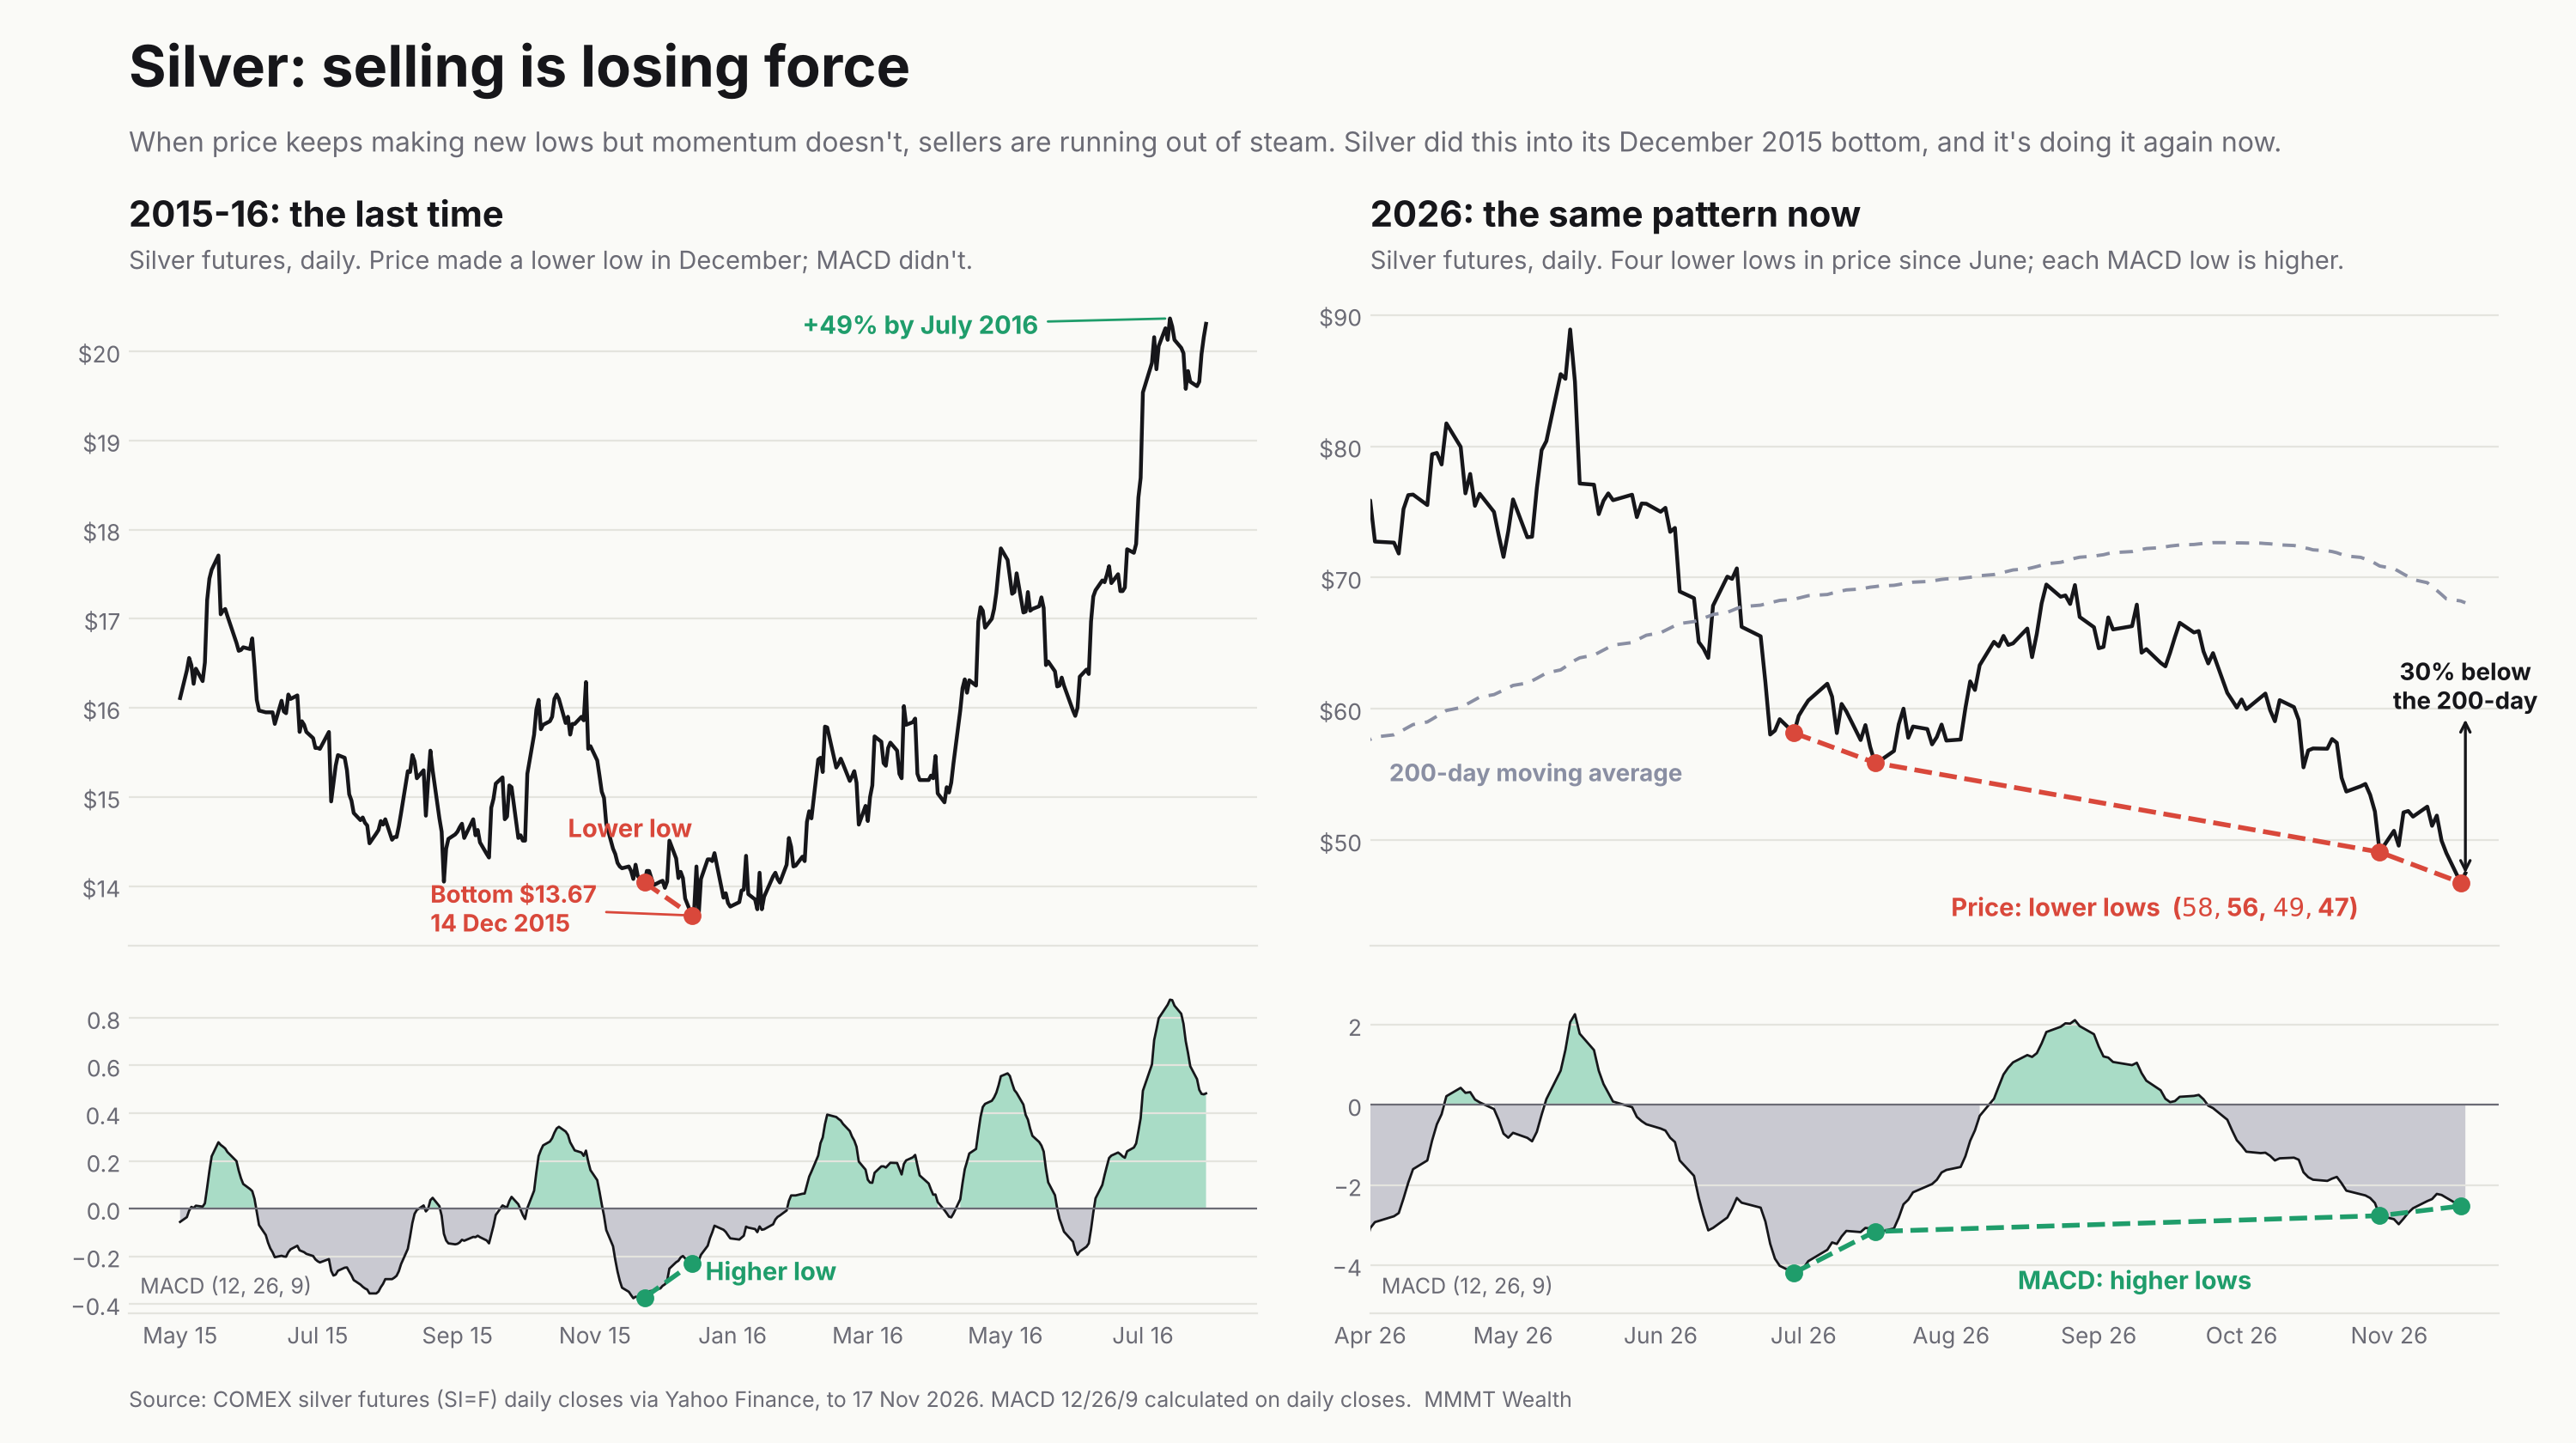
Silver: silver is more than 28% below its 200-day (and was ~32% below in early November), more extreme than the COVID crash.
Silver is also a more direct play on the AI buildout than gold. I’m far more exposed to silver than gold which adds some risk. But because I’ve been dollar-cost averaging through the decline rather than buying in one go, my average cost is well below where silver traded at its peak.
Momentum indicators like the MACD measure the strength of a move, not just its direction. Normally, when price makes a new low, momentum makes a new low too, because the selling is getting stronger. With silver we’re seeing momentum slow down
The last time this happened across the whole complex was late 2015. Silver and the miners kept grinding lower but the momentum in the selling reduced everytime. Then in January 2016 we marked the bottom of a five-year bear market in which GDX had fallen 81% and GDX more than doubled over the following six months.
Copper: no change to our view. Supply is going backwards while AI and grid demand keeps rising. I remain positioned through COPX and TMQ.
Crypto
Bitcoin lost the $75-76K support zone we’ve been watching and now sits around $64.5K. But the weekly structure hasn’t broken (yet), and until it does, I remain bullish.
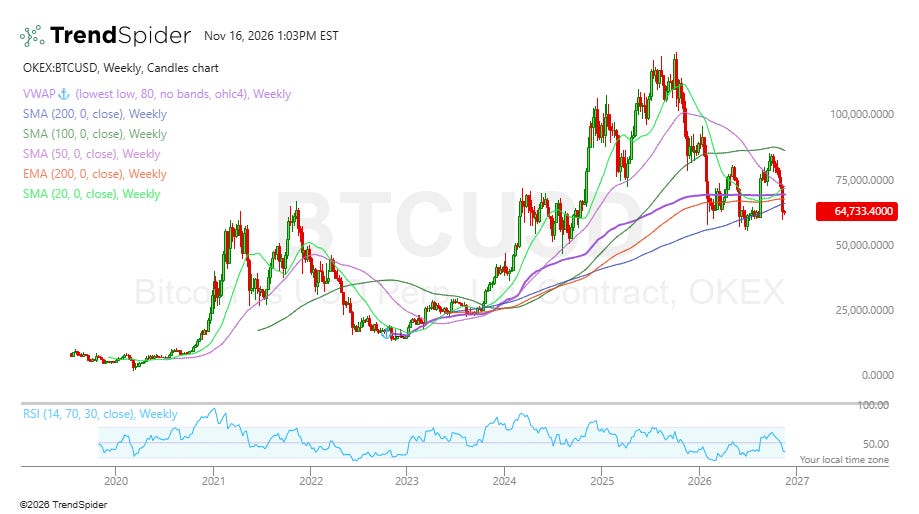
Nothing broke inside crypto itself…this was a rates and dollar move, just like we’ve seen in gold and other commodities. If the Fed stops at 25bp in December, the pressure should ease. Until then, $75K is the level to reclaim before I add more aggressively.
What’s Mispriced?
This is a section looking at the potential opportunities I’m seeing at the moment. I’ll split them by how I see the risk profile (high risk → low risk).
I aim for at least 3+ opportunities in every article I publish here but that depends on what the market is offering at the time of writing.
You’ll also likely see overlap week to week. I am not a trader that changes his mind every few hours, days, or even weeks. If I see an opportunity, that opportunity often stays around for weeks/months/years.
Last week we touched on:
Applied Optoelectronics (AAOI) - Medium Risk
TransMedics (TMDX) - Medium Risk
Nebius (NBIS) - Medium Risk
Marvell | MRVL - Medium Risk
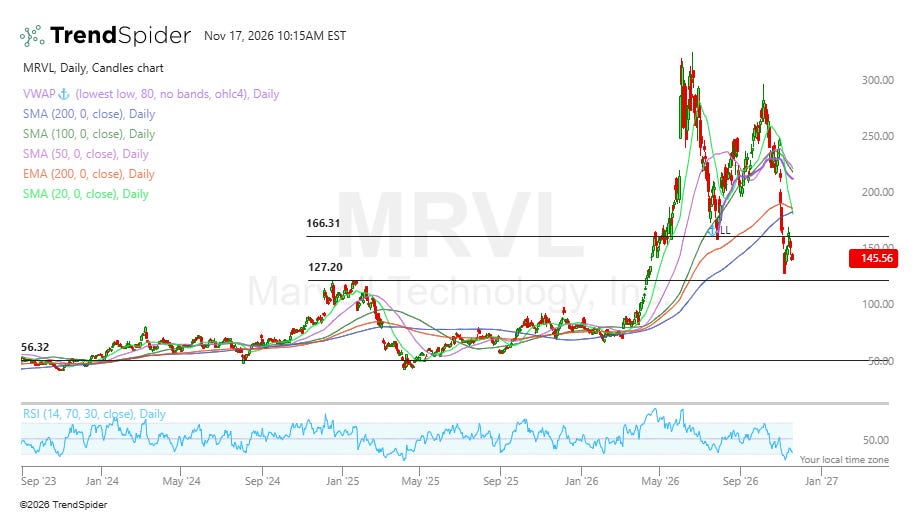
MRVL has been wiped out recently with the rest of the AI buildout names along with the news about an acquisition of Lumentum (LITE). This is missing a lot of what is actually happening though with MRVL:
Firstly, a reminder that MRVL have a deal with Google (GOOGL) giving GOOGL the option to buy ~6% of the company ($12.2B). GOOGL gets a warrant for up to 58.9M shares at $206 with the vast majority of those shares vesting over 240 tranches and each tranche only unlocking when GOOGL generates qualifying purchases between Q3 2027 and FY33.
240 * $500M → $120B of potential revenue (or ~$18B per year).
And then alongside LITE, MRVL could be generating in the region of ~$40B per year by 2029. That will essentially allow them to compete alongside the likes of NVDA and AVGO in the AI networking space.
